MarketMind: The Self-Hosted Portfolio Tracker Built to Get Dividends and FX Tax Right
Disclaimer
This post is not an investment advice.
Why I built this
Investing requires tracking your transactions: all your buys, your sells, the dividends you get paid, etc. Why? The Tax Office in your country will politely ask you to pay based on your earnings. That’s when you have two options: look for a good accountant or do it yourself. The former option might be rather expensive, and if it isn’t, maybe they’re not the best accountant around. Additionally, you would have to hand them all your transactions anyway, so you still have to do some of the work. On the other hand, the DIY choice: maybe using a spreadsheet? It sounds good, and we might be familiar with it, but it grows and grows over the years; the heavier it is, the longer it takes to fully load, and if you try to automate some metrics, it’s even worse. Once it is massively huge, you start thinking this wasn’t a good long-term idea; that’s when you realise it’s much better to use the tools we do have nowadays and bring all your investing transactions into a proper database.
At that point, I looked for some web apps, but after a while I noticed they were expensive and, what’s more, they didn’t have all the metrics I wanted. And that’s how I started MarketMind.
What it does
MarketMind is a self-hosted Django application built for portfolio tracking, dividend automation, and tax-ready gain/loss reports with real FIFO lot matching and full multi-currency support — not approximations.
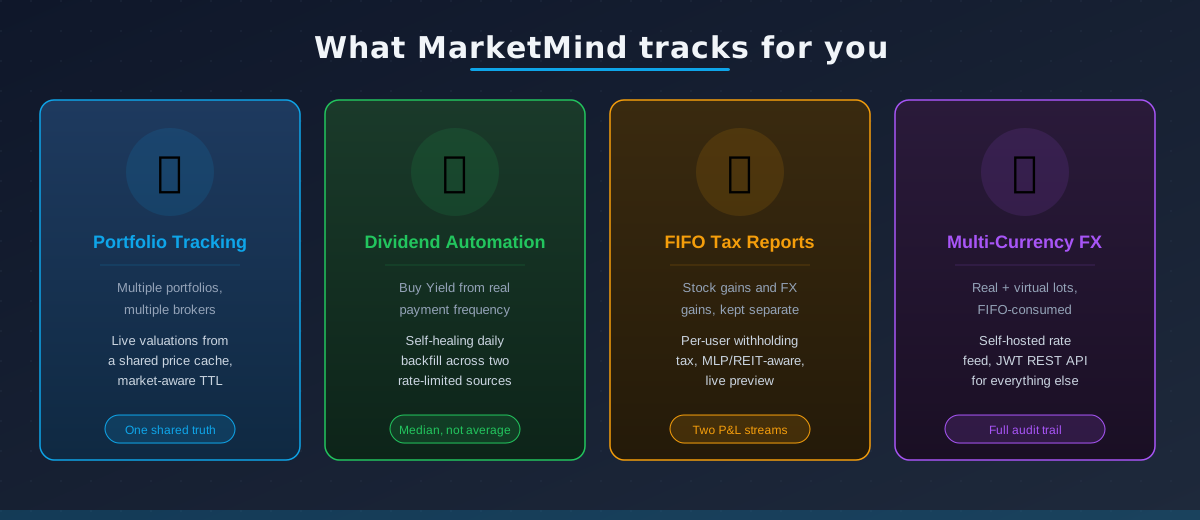
Everything lives inside per-user portfolios, each holding a full transaction book: buys, sells, dividends, interest, spin-offs, FX exchanges, deposits, and withdrawals. Positions, valuations, and dividend income all roll up from that ledger — nothing is entered twice.
| Feature | What it does |
|---|---|
| Portfolio management | Multiple portfolios, live valuations, broker-level breakdown |
| Transaction book | BUY, SELL, DIV, INT, SPOF, EXC, deposits & withdrawals |
| Live price feed | yfinance, market-aware caching, shared across every view |
| Dividend automation | Auto-synced ledger entries, frequency-aware Buy Yield |
| Tax reporting | Per-year FIFO reports, stock and FX gains kept separate |
| Withholding tax | Per-user, per-country, entity-aware (MLP/REIT) estimates |
| Multi-currency FX | Real + virtual currency lots, FIFO-consumed for tax |
| REST API | Full JSON API with JWT auth |
The sections below are the parts worth explaining in detail — not because they’re big, but because each one is solving a genuinely easy-to-get-wrong problem.
Buy Yield: The Dividend Yield You Actually Locked In
Every BUY transaction gets a buy_yield — the forward dividend yield that purchase locked in:
The effective cost includes commission; the interesting part is the numerator, which depends on two things most tools get wrong: how often the stock actually pays, and which dividend to annualise from.
Payment frequency isn’t always 4. infer_dividend_frequency takes the median gap between a stock’s actual ex-dividend dates over the trailing ~5 years and buckets it, rather than assuming quarterly:
| Median gap | Inferred frequency |
|---|---|
| ≤ 45 days | 12 / year |
| ≤ 135 days | 4 / year |
| ≤ 275 days | 2 / year |
| otherwise | 1 / year |
Using the median — not the average or a raw payment count — matters: BHP is a genuine semi-annual payer, but a couple of its recent years threw in a third special payment. Before this fix, MarketMind assumed quarterly for every stock and computed a nonsensical 24.18% Buy Yield on a BHP purchase. The median of [2,2,2,2,3,2,2,2] is still 2, so infer_dividend_frequency correctly resolves it to a semi-annual payer regardless of the outlier years.
Which dividend counts as the reference matters just as much. The naive rule — “last dividend with an ex-date before the buy” — under-counts recent buys: a purchase made the day before a newly-raised dividend goes ex-date is entitled to the new rate, not the stale one the ex-date rule would pick. MarketMind instead prefers the dividend with the latest declaration_date <= buy_date, since a publicly declared rate is locked in the moment it’s declared — regardless of whether it’s gone ex yet — and only falls back to the ex-date rule when no declaration data exists at all.
That reference is then sanity-checked against the median of the trailing 2 × frequency actual payments. If it’s more than 1.75× that median, it’s treated as a special-dividend outlier and the median is substituted instead — a real dividend raise never jumps that much in one step. For BHP, the naive reference dividend was a special-dividend-inflated $3.5682 payment (~2.8× the stock’s own recent median); swapping in the median drops the computed yield from 24.18% down to a sane 4.32%.
ETFs get a different treatment entirely: Stock.is_etf (auto-detected from yfinance) switches to summing the last frequency distributions rather than extrapolating from any single one, since ETF payouts vary shipment-to-shipment with no board-declared rate to lock in.
Two Ledgers, One Tax Report
Most tax authorities want stock gains and currency gains reported separately — and mixing them, as a plain spreadsheet does, produces a P&L that’s technically wrong even if the total happens to net out correctly. MarketMind keeps them apart by running two independent FIFO systems side by side.
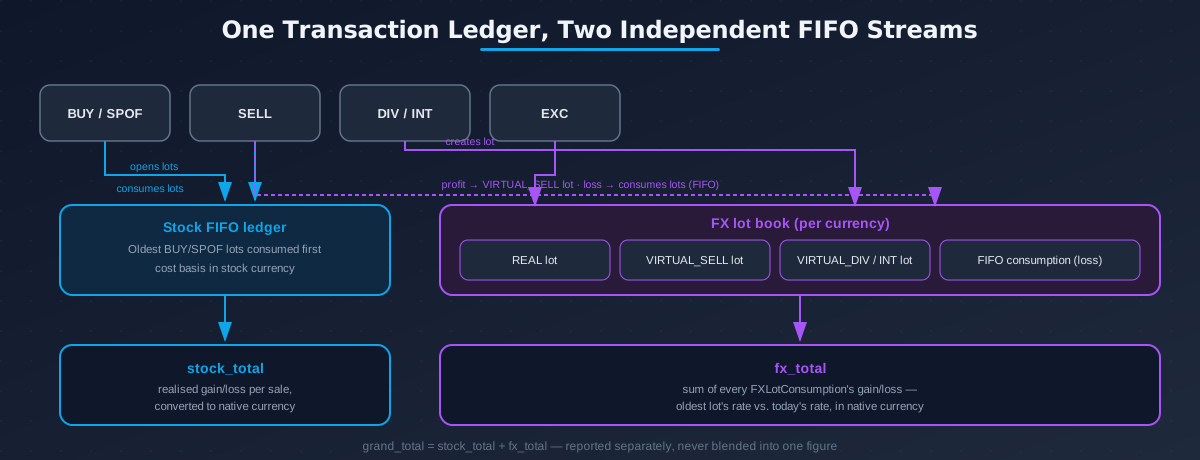
Stock P&L is the familiar one: for a SELL, walk the portfolio’s BUY/SPOF history for that symbol oldest-first, consume shares FIFO, and the cost basis includes commission amortised per share. This produces the gain or loss in the stock’s own currency, which is then converted to the portfolio’s native currency using the FX rate on the sell date.
FX P&L is the part most trackers skip entirely. Every foreign-currency event creates an FXLot in the currency book:
| Event | Lot type |
|---|---|
EXC (currency exchange) |
REAL — actual foreign currency purchased |
SELL with profit vs. FIFO cost |
VIRTUAL_SELL — proceeds “received” in stock currency |
SELL with loss vs. FIFO cost |
consumes existing lots instead of creating one |
DIV / INT |
VIRTUAL_DIV / VIRTUAL_INT — income received in its own currency |
When foreign currency “leaves” the book — spending it, or a SELL landing below cost basis — it’s matched against the oldest open lots first, exactly like the stock-side FIFO. Each match creates an FXLotConsumption record: the amount consumed, the FX rate at the original lot’s creation versus the rate now, and the resulting gain or loss in native currency. A euro-denominated investor who bought USD at 1.05, held it through a stock sale, and converted back at 1.12 has a real, separately-reportable FX gain — captured automatically, with a full audit trail of exactly which lot funded which transaction.
The result: TaxReportService.calculate returns a stock_total and an fx_total as genuinely independent numbers for a given year, not a single blended figure that happens to add up.
Withholding Tax, Per User, Per Entity Type
Dividend withholding is personal — two people holding the same stock can owe completely different origin-country rates depending on residency, treaty status, and paperwork on file. get_withholding_tax_rate(user, stock) resolves it through three layers, most specific first: a rule for that exact stock, then a rule for the stock’s country + entity type, then a country + REGULAR fallback. Nothing matches → the rate is None and tax stays 0 rather than guessing.
The entity-type layer exists because not all dividends are alike. Stock.entity_type is auto-classified once, the first time a stock is seen (never touched again, so a manual correction sticks): a name containing “L.P.” is an MLP (effectively-connected income, not treaty-reducible — a much higher US withholding rate than a regular dividend), a “Real Estate” sector is a REIT (genuinely treaty/case-specific), everything else is REGULAR. A confirmed test case makes the difference concrete: a $20 gross EPD (MLP) dividend withholds $7.40 at 37%, while a $5 gross MSFT dividend withholds $0.75 at 15% — same mechanism, very different outcomes depending purely on entity type.
The whole lookup also runs client-side in the transaction form: a small JSON blob of every tracked stock’s {country, entity_type} plus the user’s own rules is embedded in the page, so the “Tax Withheld” field auto-fills as you type — no round trip, and still just an editable preview for the odd case (a partially-franked dividend) that needs a manual override.
Dividend Data That Heals Itself
Dividend history comes from two routed sources — FMP for US-listed stocks, Alpha Vantage for everything else — falling back to yfinance when both are unavailable. Both give full history including declaration_date in a single request per symbol, which is what Buy Yield’s declaration-date preference depends on. But FMP premium-gates a rotating, unpredictable subset of well-known US tickers (CAT, HON, MO, WDS — no way to know which in advance short of calling live), and Alpha Vantage’s free tier caps out at 25 requests/day.
Rather than leaving gaps, a daily cron (backfill_dividend_declaration_dates, run right after the nightly DB backup) closes them automatically: it retries any FMP failure through Alpha Vantage before giving up, processes non-US stocks first so that fallback spending never starves the symbols that genuinely depend on Alpha Vantage, and tracks a declaration_date_checked flag per dividend so a source that genuinely has nothing doesn’t get re-queried — and burn quota — every single day forever. recompute_buy_yields then reruns behind it, so any yield computed while data was still incomplete gets silently corrected within a day or two, with no manual intervention.
Live Prices Without Hammering Yahoo Finance
PriceCacheService fronts every price lookup with a market-aware TTL: a 15-minute cache during NYSE regular hours (matching yfinance’s own 15-minute delay), stretching to 2 hours once the market’s closed. Every page shares the same per-symbol cache key, so two views can never disagree on a price, and the day’s OHLC is lazily persisted to HistoricalPrice in a background thread after close — turning the live feed into next season’s historical data with no separate ETL step.
Under the Hood
| Layer | Technology |
|---|---|
| Backend | Django 5.0.1, Django REST Framework, served by gunicorn |
| Database | PostgreSQL 15 |
| Market data | yfinance, FMP + Alpha Vantage (dividend history) |
| FX rates | Self-hosted Frankfurter v2 instance, reached over Tailscale |
| Authentication | django-allauth (Google OAuth) + djangorestframework-simplejwt |
| Frontend | HTML5, CSS3, vanilla JavaScript |
| Static files | WhiteNoise |
| Containerisation | Docker + Docker Compose, image published to GHCR |
Production deployment sits behind a Cloudflare Tunnel with no extra infrastructure — settings.py already trusts X-Forwarded-Proto/Host, and the only required step is pointing CSRF_TRUSTED_ORIGINS at the tunnel domain (skip it and every POST comes back a 403, Django’s CSRF layer rejecting an origin it doesn’t recognise). FX rates come from a self-hosted instance of my own Frankfurter v2 fork — one project’s infrastructure quietly powering another’s.
Choosing the stack
After accumulating some experience with Django thanks to QATrack+ and Wheeler Keeper, I chose it again to build this project; as I mentioned in the Wheeler Keeper post, Django provides a native admin panel to manage the app, an incredibly easy translation from code to database thanks to its ORM and migration system, while the django-allauth package lets users sign up with a social account, such as Google. And once more, PostgreSQL was the chosen database, over SQLite, due to its better handling of simultaneous changes in the database.
The combination of yfinance alongside FMP and Alpha Vantage free tiers made populating the database robust and quick, without waiting too long for the free-tier quota to reset. The discovery of Frankfurter as a currency converter API was the key piece of this web app, but why self-host a fork instead of calling the public API? Well, since it is open source, we can host it as well; if somehow the website is down or it is no longer available in the future, you have a copy running on your server. And the fork lets me adapt it to my server: a different default port, a Docker Compose setup, and updated provider coverage dates.
The use of cron jobs keeps the database updated with dividends, Buy Yields and financial metrics such as payout ratios, which is vital for being your own accountant without spending too much time manually writing down all your dividend payments.
Finally, the whole web app is containerised with Docker for easy deployment.
What I learnt
I had decided to make daily backups of the whole database, just in case it gets erased by mistake, and, as a bonus track and safety measure, I also wanted to save the backups somewhere else, outside the home lab. After digging a little, and thanks again to Tailscale, I managed to do so by having my laptop pull the latest backup whenever it starts up; here you have detailed instructions on how to do it. Having a backup copy of your backups may sound quite redundant, but it is vital so as not to lose your investing information.
Getting Started
The live instance is available at market-mind.box2overtake.com. The source is on GitHub.
Your portfolio already has all this data in it. MarketMind is just the part that does the arithmetic properly.
Last modified: 12 Nov 2026